Homebuyers naturally focus on location, views, bedrooms, kitchens, land, and monthly mortgage payments. In Arizona’s high country, another conversation belongs near the beginning of the buying process: insurance.
Insurance availability and pricing can vary from one property to another, particularly when homes are rural, heavily wooded, older, difficult to access, or equipped with features that require additional underwriting.
Checking insurance early can help buyers understand the true cost of ownership before becoming committed to a particular home.
Insurance Is Property-Specific
Two houses in the same general area may receive different insurance quotes.
Construction type, roof age, heating source, vegetation, prior claims, access, nearby fire protection, property condition, square footage, outbuildings, and other characteristics may influence an insurer’s review.
For this reason, a quote from a friend or neighbor should not be treated as a reliable estimate for another property.
Buyers should provide the insurer with the exact property address and accurate details whenever possible.
Wildfire Is Important, but It Is Not the Only Consideration
Wildfire receives considerable attention in Arizona, especially in forested communities.
But insurers may evaluate many additional risks.
Winter freezes can affect plumbing. Heavy snow can place stress on roofs and decks. Wind can damage roofing and trees. Older electrical systems may require review. Wood-burning stoves, fireplaces, propane systems, detached structures, and certain roof materials may also generate questions.
A mountain home needs to be evaluated as a complete property.
Roof Age Can Matter
Buyers often focus on whether a roof currently leaks. Insurers may also care about its age, material, remaining useful life, and overall condition.
A roof that appears functional during an inspection may still affect available coverage or pricing.
Ask the seller for documentation when substantial roof work has been completed.
Knowing the approximate age of the roof before requesting quotes can make insurance conversations easier.
Access Can Influence the Bigger Picture
Remote properties are attractive to many White Mountains buyers, but access should be considered from several angles.
An insurer may want accurate information about road conditions, year-round access, nearby emergency services, and the ability of responders to reach the home.
Buyers should also think beyond insurance.
If a road becomes difficult during snow or monsoon weather, that can affect maintenance crews, deliveries, propane service, emergency response, and daily life.
Wood Stoves and Alternative Heat Sources
Wood-burning stoves are common and appealing features in mountain homes.
Insurers may ask questions about the installation, age, chimney, maintenance history, or whether the system meets applicable standards.
The same principle can apply to fireplaces, pellet stoves, propane equipment, and other heating systems.
Buyers should describe the property accurately rather than discovering an underwriting issue late in escrow.
Ask About Deductibles, Not Just Premiums
The cheapest annual premium is not necessarily the least expensive policy when a claim occurs.
Buyers should understand deductibles, exclusions, coverage limits, replacement-cost provisions, personal-property coverage, detached-structure coverage, and any special conditions.
Second homes may also be treated differently from primary residences.
If the property will be vacant for extended periods, rented, or used seasonally, tell the insurance professional how the home will actually be used.
Start Before the End of Escrow
Insurance should not be treated as a final-week task.
Once a buyer becomes seriously interested in a property, requesting preliminary information can identify concerns while there is still time to evaluate alternatives.
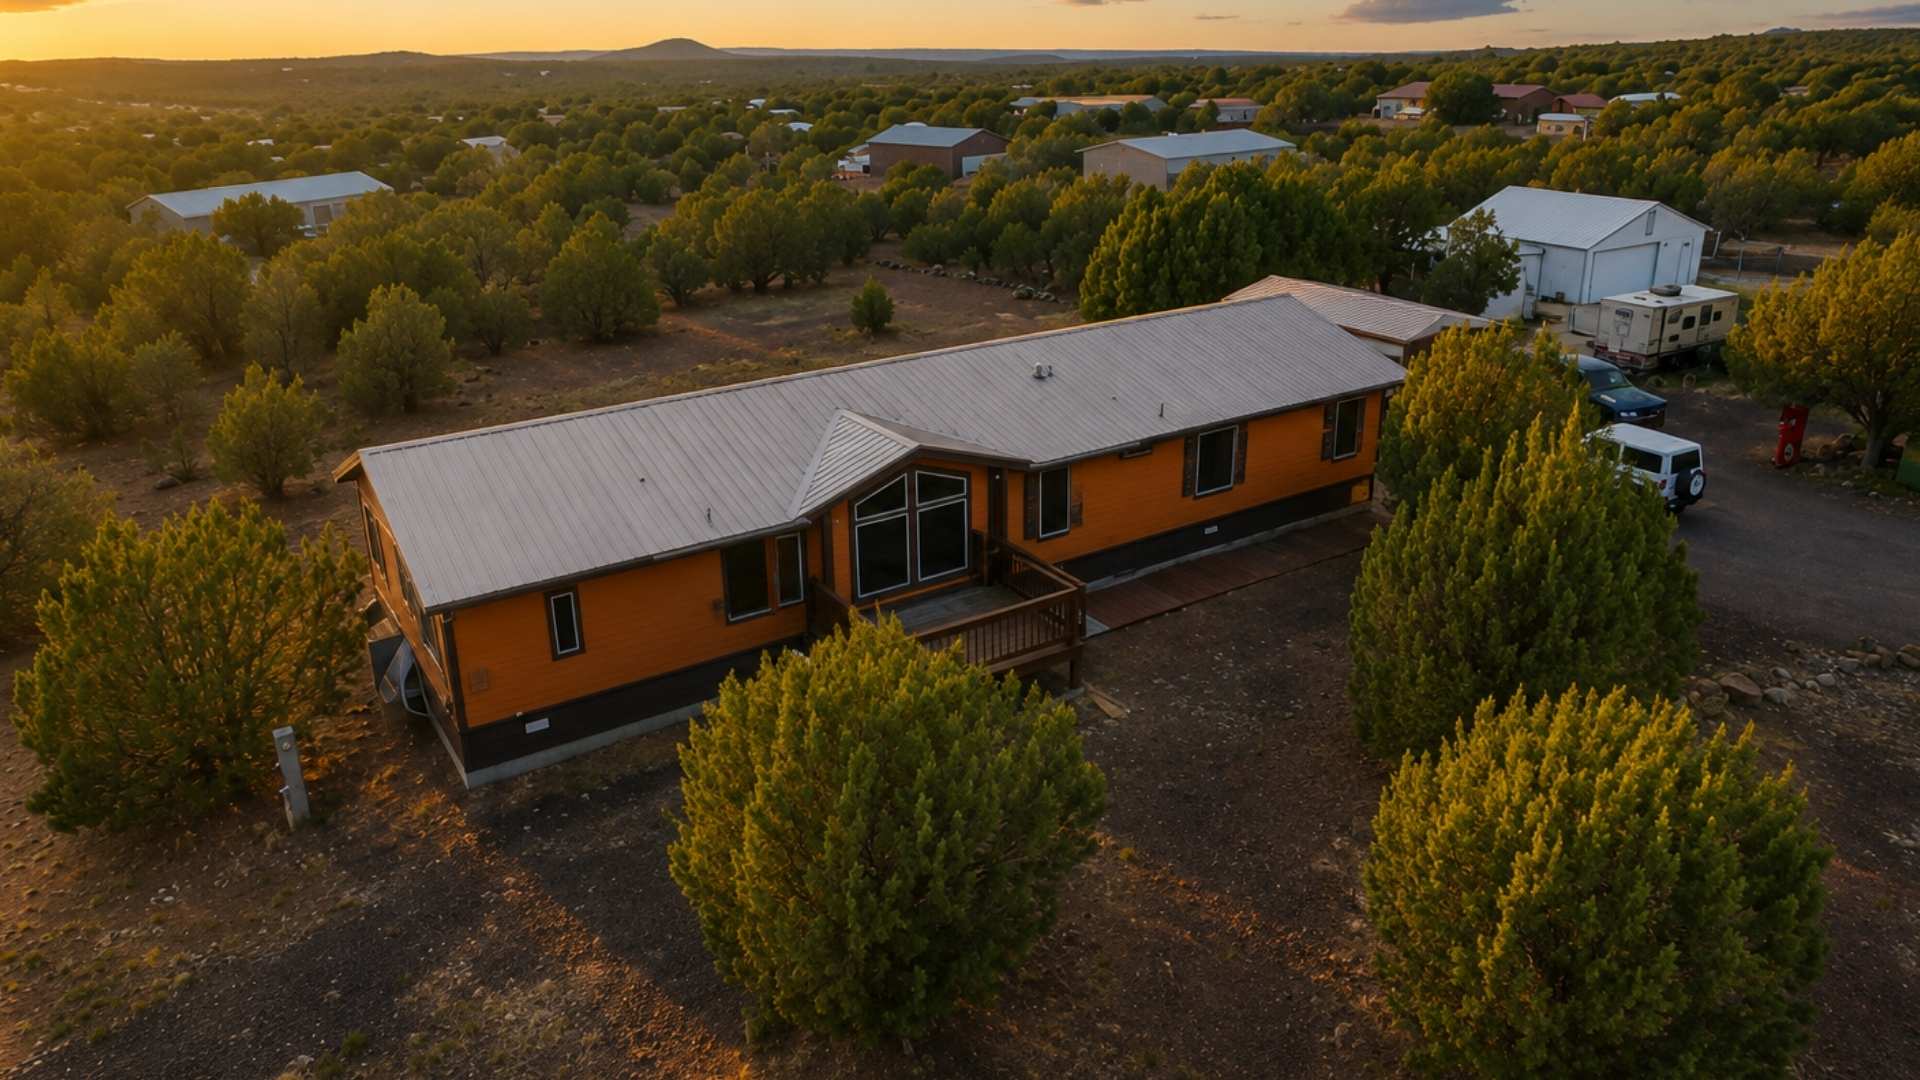
This is particularly valuable with older homes, cabins, heavily wooded properties, unusual construction, manufactured homes, or residences in remote locations.
Sellers Can Prepare Too
Sellers can make the process easier by keeping useful property information available.
Roof replacement records, electrical upgrades, plumbing work, HVAC records, defensible-space maintenance, chimney service information, permits, and documentation of significant improvements may help answer buyer questions.
Organized information builds confidence.
It also reduces the need to reconstruct years of property history during a time-sensitive transaction.
Final Thoughts
Insurance is one part of the total ownership equation.
A mountain home may still be an excellent fit even if its insurance considerations are different from those of a suburban property. What matters is understanding those considerations before closing.
For buyers in Show Low, Pinetop-Lakeside, Heber-Overgaard, and throughout Navajo and Apache Counties, an early insurance conversation can provide clarity about both affordability and long-term ownership.
Stefan and Kim Wehnau help White Mountains buyers evaluate the complete property picture, not simply the features visible during a showing.
Call or text: 928-242-9677
Email: WeKnowAZRE@gmail.com